Buying a home, moving out, getting married, having children—each seems to be happening later. We often say younger generations simply want different things. But perhaps what changed first was not what they wanted. Perhaps it was the road they were asked to travel.
Imagine someone approaching 30 who still lives with his parents. He graduated from college, has a steady job, contributes to household expenses, and saves part of every paycheck. He is not particularly extravagant, nor is he living entirely at his parents’ expense. Given today’s rents and home prices, staying home for a few more years while building savings may be one of the most rational financial decisions he can make.
And yet, at a family gathering, someone asks:
“You’re still living with your parents?”
The question may be harmless, but it lingers. A friend buys a house. Another posts wedding photos, followed a year or two later by pictures of a new baby. Without meaning to, he begins measuring his life against theirs. He has a job. He is saving. He is planning for the future. And still, a thought creeps in: Why am I still here?
To his parents’ generation, the situation may look even stranger. Many were already married at his age. Some had bought modest homes. Some already had children. And so it becomes easy to say that young adults today are taking longer to grow up.
But is he really late? Or are we measuring his life with an old timetable?
The Road Changed First
For much of modern American life, adulthood was imagined as a fairly familiar sequence: finish school, get a job, leave your parents’ home, get married, buy a house, have children, then begin preparing for retirement.
The past, of course, was never that simple. Earlier generations endured recessions and periods of punishingly high interest rates, while women and racial minorities faced barriers far greater than many do today. It would be historically careless to say that life was easy for previous generations and uniquely difficult for this one.
Still, that sequence became a powerful social benchmark. We learned to judge where someone “should” be by a certain age, and milestones such as living independently, marrying, owning a home and having children became more than personal choices. They became visible evidence that someone had become an adult.
But the timetable of actual life has already moved. In 1975, the median age at first marriage in the United States was 23.5 for men and 21.1 for women. By 2025, it had risen to 30.8 and 28.4. That same year, 58% of Americans ages 18 to 24 and 16% of those ages 25 to 34 were living in their parents’ home.
It is tempting to explain this simply as a change in values, and values certainly have changed. Women have far greater economic independence and choice. Marriage no longer carries the same expectations it once did. Remaining child-free has become a legitimate life choice for many, while others value mobility and flexibility more than homeownership. It would therefore be equally simplistic to assume that young adults want exactly the same lives their parents had but simply cannot afford them.
Place those changing values beside today’s economic conditions, however, and another picture begins to emerge.
Between 2019 and 2024, inflation-adjusted median household income among U.S. households under 40 rose about 9%, while median home values rose roughly 30%. Add higher mortgage rates, and Pew Research Center estimated that typical monthly homeownership costs rose from $1,689 to $2,776—an increase of about 64%. Over the same period, the share of renters under 40 with enough income to afford those monthly ownership costs fell from 56% to 37%.
But the more revealing part of the story is not simply that houses became more expensive. When it takes longer to afford a house, more than the date of a home purchase moves. Someone may stay with parents longer to save for a down payment. Delayed independence may alter marriage plans. High housing costs after marriage may affect when a couple feels ready for children. Student debt, retirement savings, insurance and childcare are all drawing from the same paycheck, which means these decisions can no longer be treated as separate financial events.
That is what gets lost when we simply say, “Everything is more expensive now.” It is not only that the price of one future has gone up. Several different futures are now competing for the same paycheck.
Save more for a house and another form of saving may have to wait. Pay off student loans first and the down payment takes longer. Have a child and housing costs suddenly coexist with childcare costs. Once financial pressure on one stage of life begins changing the timing of the next, money becomes something else.
It becomes time.
And from that point forward, economics alone can no longer explain the story.
When Money Moves Time, Time Begins to Move Culture
Deloitte’s 2026 survey of more than 22,500 Gen Z and millennial respondents across 44 countries found that 55% of Gen Z and 52% of millennials had delayed major life decisions because of financial concerns. Housing affordability and availability also affected career decisions and where to work for 69% of Gen Z and 64% of millennials.
The revealing word here may be not “abandoned,” but “delayed.” Someone may still want a house but conclude that now is not the time. A couple may still want children but decide they need more stability first. A worker may want to change jobs but decide that giving up current security is a risk they cannot yet afford.
Nor does this necessarily describe a generation that has given up on the future. In the same Deloitte survey, 53% of Gen Z and 45% of millennials expected their personal financial situation to improve over the following year. Many appear to be postponing decisions under pressure without abandoning the future they imagine for themselves.
That distinction matters. When one person delays marriage for two years because of housing costs, it remains a private economic decision. When millions make similar decisions, something larger begins to happen. The average age of marriage moves. People remain with parents longer. The timing of homeownership and childbearing shifts. What begins as an adaptation to economic conditions can, if repeated long enough, become an ordinary way of living.
Eventually, we stop calling it economic adaptation. We call it culture.
So when we hear that young people marry later now, or that they care less about owning a house, another question is worth asking. Did values change first and produce new behavior, or did behaviors adopted in response to new economic conditions gradually become part of a new set of values?
Reality is probably moving in both directions. Values have changed, and economic conditions have changed. What matters is that they do not move independently. Economics changes choices; repeated choices change culture; and the culture that emerges begins shaping the choices that follow.
Some of what we casually describe as the personality of a generation may therefore be, at least in part, the imprint of the economic environment that generation encountered.
That raises a more difficult question. If people’s actual lives have adjusted to new conditions, have our expectations of what a normal life should look like changed at the same speed?
It does not appear that they have.
Marriage ages have risen. Living with parents into adulthood has become more common. The economics of buying a home have changed dramatically. In other words, the timetable of actual life has already moved. Yet we still look at a 30-year-old living with parents and ask, “Still?” We still ask unmarried adults when they are finally going to settle down. And young adults themselves, fully aware of today’s economics, can still feel behind when a friend buys a house.
Something important becomes visible here that individual statistics about housing or marriage tend to obscure:
The economic timetable and the cultural timetable are moving at different speeds.
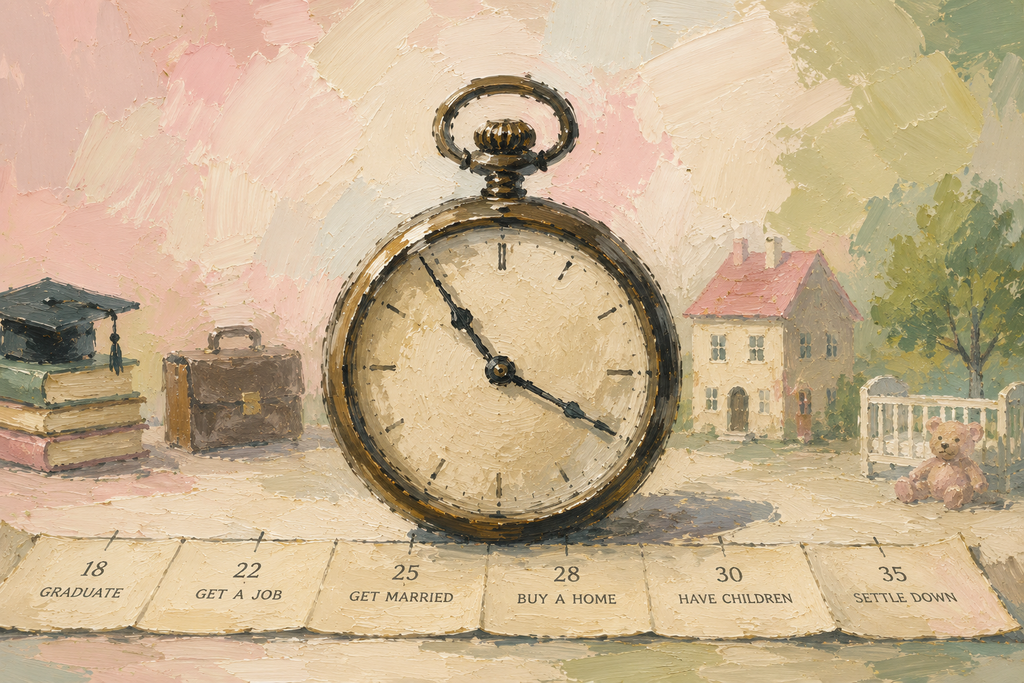
The economic timetable responds relatively quickly to housing prices, wages, employment and education costs. People delay home purchases, remain with parents longer, and adjust marriage or childbearing plans. The cultural timetable is slower. It remains embedded in our parents’ experiences, comparisons with our peers, the families we grew up watching, and old assumptions about where someone “should” be at a certain age.
That makes it possible to live rationally according to today’s economy while judging yourself according to yesterday’s timetable. Staying with parents and saving aggressively may be financially wise, yet still feel like a failure to launch. Delaying marriage may be the right decision for a couple, yet a friend’s wedding can still produce the uncomfortable sensation of being behind.
The gap between economic time and cultural time is then carried not by society as an abstraction, but by individuals as emotion.
The cost of adulthood may not be only financial. It may also be the cost of feeling late.
Housing, rent, tuition and childcare can be measured in dollars. The cost of living rationally in one era while feeling that you have failed the expectations of another does not appear in any economic statistic.
The Paradox of Family
Follow that thought a little further and another paradox appears. We have long associated adulthood with becoming independent from one’s parents, yet as the price of economic independence rises, parental resources may become more important in reaching it.
Someone who can remain at home for several additional years may save money that would otherwise disappear into rent. Parents who can contribute to a down payment may help a child enter the housing market sooner. Grandparents who can provide childcare may make it easier for two parents to remain in the workforce. Research on parental financial transfers and young-adult homeownership has likewise found an association between parental assistance and the transition into homeownership.
This complicates the way we usually think about inequality. Imagine two 30-year-olds who each earn $80,000 a year. One can live with parents for several years and redirect what would have been rent toward a down payment. The other must pay substantial rent throughout those same years. Their incomes are identical, but it is difficult to imagine that their economic positions several years later will necessarily be the same.
Income, in other words, may not be the only difference that matters. There may also be a difference in how long someone can afford to wait.
Years in which someone does not have to rush out of the family home, years in which rent can become savings, or years in which relatives can help with childcare can all create room for the next decision. Seen this way, families may pass something to the next generation besides money and property.
They may also pass down the ability to wait.
There is a peculiar irony in that. In a society that has long treated independence from family as one of the clearest markers of adulthood, achieving independence may increasingly depend on what kind of family support a person has available.
That, in turn, forces us to ask what we have actually been measuring when we call someone an adult. A home, a separate address, marriage, children and a stable career are visible. Responsibility, restraint, judgment and the ability to live with the consequences of one’s choices are much harder to see. Perhaps we have sometimes used visible economic outcomes as proxies for something far more difficult to measure: maturity.
Maturity should not have a price tag. But many of the things we have used as evidence of maturity do—and their prices have changed.
Owning a home, establishing a household and raising a family can remain deeply meaningful goals without requiring us to assume that the age at which someone reaches them is a reliable measure of how fully that person has grown up.
Where Does Delayed Time Go?
There is one more question, and it points forward. If buying a home happens later, and marriage and childbearing move later as well, it is tempting to imagine that the entire course of life simply shifts backward by several years.
But not every clock in life moves together.
Parents continue to age. Fertility has biological constraints. Retirement eventually arrives. Responsibilities delayed in early adulthood may therefore not disappear; some may meet one another later within a narrower stretch of life. A person may be raising children when aging parents begin to need care. A mortgage may coexist with college expenses and the need to accelerate retirement savings.
In a 2025 survey, 54% of Americans in their 40s had both a parent age 65 or older and either a minor child or an adult child they were financially supporting—the group commonly described as the “sandwich generation.” Across all U.S. adults, the figure was 25%.
It would be a mistake to claim that delayed marriage or homeownership caused this. Longer lifespans, support for adult children and many other forces are involved. But the phenomenon raises a question worth watching: are the stages of adult life simply moving later, or are housing, childrearing, eldercare and retirement preparation beginning to compress into a narrower portion of adulthood?
If so, some of the rising cost of adulthood may not be paid only in dollars today. Time postponed earlier in life may return later in the form of overlapping responsibilities. That possibility requires much more study, but it suggests that “young people are doing everything later” may be far too simple a description of what is happening. The structure of time across adult life itself may be changing.
And by this point, our view of the nearly 30-year-old still living with his parents has changed as well. At the beginning, we asked why he had not yet left home. But once his economic circumstances and the future he is preparing for are considered together, the more interesting question may no longer be why he has not yet become an adult.
It may be what, exactly, we mean by adulthood now.
Perhaps younger generations are not simply arriving later at the old destination. As the relationships among money, family, marriage and work change, the destination itself may be moving.
The Old Clock
For a long time, we have looked at a person’s age and used it to judge where that person should be in life. By 30, we imagined independence. Somewhere around there, marriage, a home and children were supposed to begin appearing too.
But what if the road itself has changed?
What if we are demanding the same arrival time from people who are no longer traveling the same distance?
Personal responsibility still matters. Working hard, saving, making choices and accepting their consequences have not become irrelevant.
But before declaring that an entire generation is running late, there is one thing worth checking.
Are they really late—or are we still looking at an old clock?
TENVER VIEW
For generations, we have treated leaving home, marriage, homeownership and children not simply as life events, but as evidence that someone has successfully entered adulthood.
The problem is that the price and timing of those milestones have changed faster than the expectations surrounding them.
Perhaps the question, then, is not whether adulthood still requires responsibility. It does. The question is whether we should continue measuring that responsibility by a timetable built under different economic conditions.
Responsibility and arriving “on time” are not necessarily the same thing.
Sources
U.S. Census Bureau — America’s Families and Living Arrangements: 2025
Median age at first marriage and the share of young adults living in their parental home.
Pew Research Center — Buying a Home Has Gotten Harder for Young Adults in Most U.S. Metro Areas
Home prices, household income, mortgage costs and affordability among households headed by adults under 40.
Deloitte — 2026 Gen Z and Millennial Survey
A global survey of more than 22,500 Gen Z and millennial respondents across 44 countries, including financial pressures, housing concerns and delayed major life decisions.
Harvard Joint Center for Housing Studies — The Role of Parental Financial Assistance in the Transition to Homeownership by Young Adults
Research examining the relationship between parental financial transfers and young adults’ transition into homeownership.
Pew Research Center — More Than Half of Americans in Their 40s Are “Sandwiched” Between an Aging Parent and Their Own Children
Data on Americans simultaneously navigating responsibilities involving their children and aging parents.
답글 남기기